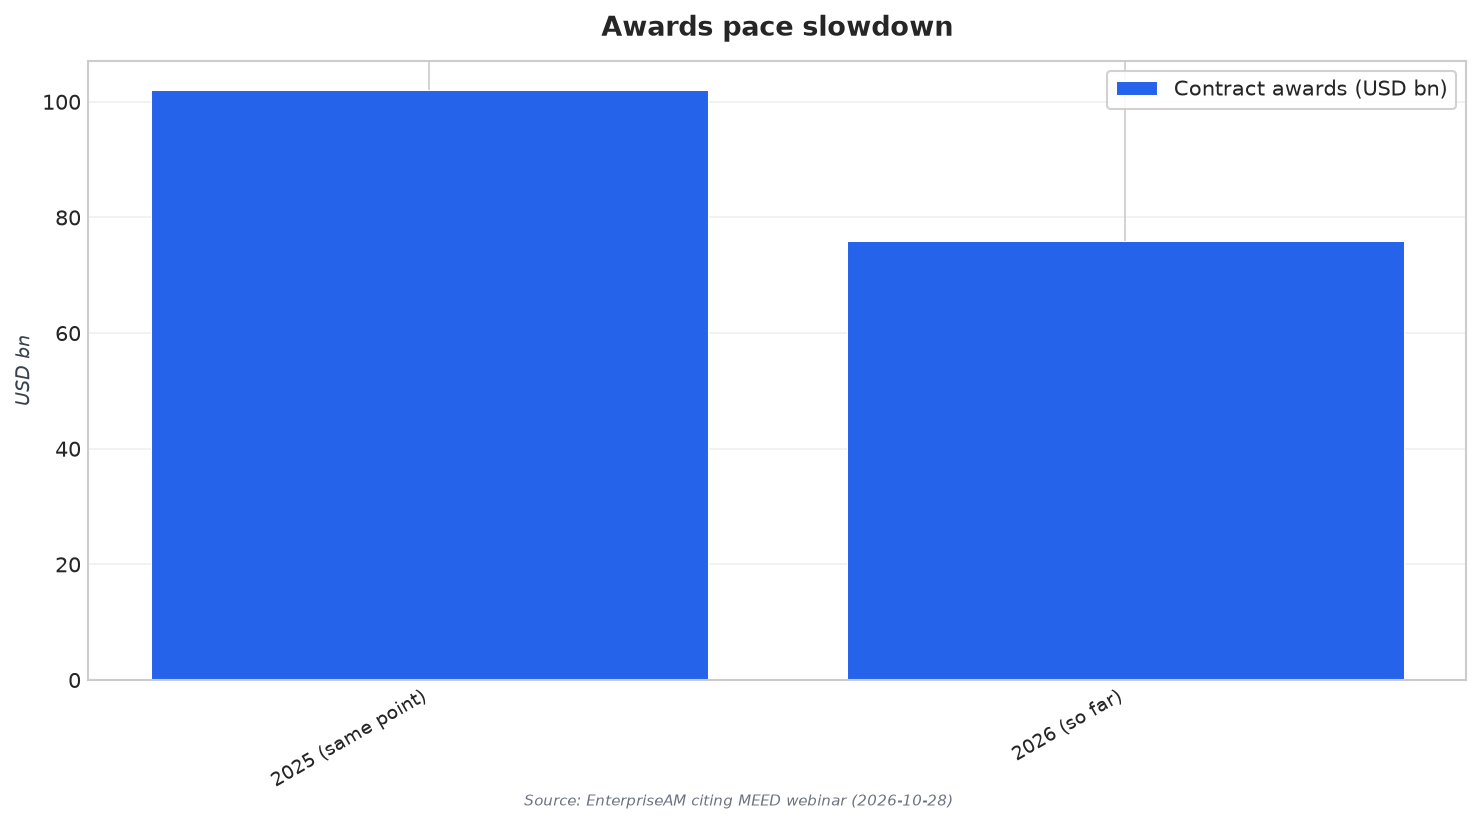
Saudi Arabia’s projects market has awarded USD 76 bn in contracts so far in 2026, compared with USD 102 bn at the same point in 2025. That gap frames the current narrative around a Saudi project awards decline in 2026 and what it means for the contractor pipeline. Yet expectations still lean toward momentum into year-end: Meed expects a run of awards in November and December that could lift the full-year figure to USD 100 bn. The contrast matters because it suggests timing and composition shifts, not a simple stop in activity, even amid regional conflict, cost inflation, and supply disruption.
Sentiment, however, is materially weaker than the headline totals. In a webinar poll, 70% of attendees said the market performed worse than 2025, with 50% calling it a little worse and 20% much worse; only 8% said it improved. Another poll found 94% saw their business disrupted by the year’s regional conflict, and 30% said the disruption was severe. For pipeline planning, that combination typically shows up as slower decision cycles, tighter bid filters, and heavier emphasis on contracts where scope and delivery risk are clearly defined.
Where the Slowdown Is Concentrated—and Where It Isn’t
The 2026 dip is concentrated in utilities that already built ahead. Power awards are down 77% year over year to USD 4.9 bn, and water is down 66% to USD 3.7 bn, reflecting eased need after large tendering across 2023, 2024, and 2025. Excluding utilities, the picture reverses. Construction awards have already hit USD 32 bn with two months left and are positioned to beat last year’s USD 33 bn. Gas is at USD 10.6 bn, chemicals at USD 6.1 bn, and transport at USD 10.3 bn, all running ahead of 2025, with industry set to follow at USD 5 bn.
Gigaprojects are slowed, but the market’s center of gravity is broader than a single program. Awards tied to gigaprojects reached USD 10.6 bn in 2026, and even at the 2023–2024 peak they represented USD 31 bn of more than USD 130 bn awarded in 2023 and USD 26 bn of a record USD 170 bn in 2024. Reprioritization at NEOM pushed back The Line and Trojena, while Qiddiya and Diriyah were described as “full steam ahead,” with Roshn and the Expo build-out also going strong. For contractors, that argues for a portfolio pipeline across multiple clients and sectors, not a single-bet strategy.
Two pipeline forces stand out: data centers and cost risk. Active data center projects in the Kingdom reached USD 180 bn, up from USD 1.8 bn in 2023. At roughly USD 10 mn per MW, Humain’s planned 6 GW AI campus alone implies something on the order of USD 60 bn of spending, with Humain, DataVolt, Khazna, and Amazon Web Services building. Meanwhile, most work is let on lump-sum terms with no cost-escalation clause, leaving contractors exposed when inputs move; increases of up to 70% were cited in extreme cases tied to the conflict, with local prices for rebar, copper wiring, steel, and aluminum up 4–6%. Rebuilding a contractor pipeline in 2026, in this context, means selecting bid targets where price risk is survivable and capacity can be staffed without overextending.
What do the 2026 award figures in Saudi Arabia show versus 2025?
Which sectors saw the steepest declines in Saudi awards during 2026?
Which sectors are running ahead of 2025 in Saudi Arabia’s 2026 market?
How are data centers changing Saudi Arabia’s contractor pipeline outlook?
How should contractors interpret the Saudi project awards decline in 2026 when rebuilding their pipeline?
Talk to us for your needs in:
-
Sustainable Construction Solutions
-
Strategic Construction Planning
-
Customer-Centric Construction Services
-
Operational Excellence in Construction
-
Leadership and Change Management for Construction
-
Digital Transformation in Construction
-
Saudi Construction Market Research
-
In-Depth Market Study for Construction
-
Market Intelligence and Insights in Construction
-
Feasibility Study and Assessment in Construction
-
Saudi Construction Benchmarking